Interest affects how quickly your savings grow and how much you may pay when you borrow money. Two common methods, simple interest and compound interest, use different calculations. Understanding that difference can help you compare financial products with greater confidence.
How Simple Interest Works
Simple interest uses the original amount, or principal, throughout the calculation. For example, imagine you place $2,000 in an account with a 4% annual simple interest rate.
After one year, the account earns $80. If the same rate and principal remain in place, the account earns another $80 the following year. The interest does not increase the amount used for the next calculation.
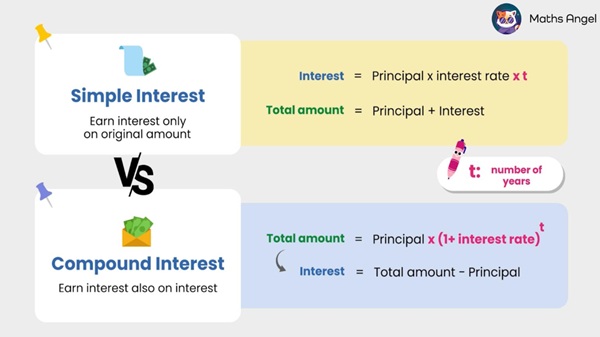
You can calculate simple interest with this formula:
I = P × r × t
Here, P represents the principal, r represents the interest rate, and t represents the time period.
As a result, simple interest usually produces a steady increase when the rate and principal stay unchanged.
How Compound Interest Works
Compound interest follows a different approach. When an account adds interest to the balance, that new balance can generate more interest during the next period.
For instance, start with the same $2,000 and a 4% annual rate. After the first year, your balance reaches $2,080. During the second year, the calculation uses $2,080 instead of the original $2,000.
Therefore, each period can add slightly more interest than the previous one.
You can represent annual compound growth with this formula:
A = P(1 + r)ᵗ
The final amount depends on several factors, including the starting balance, interest rate, time, and compounding schedule.
Compound Interest vs. Simple Interest
The main difference comes down to the balance used for each calculation.
| Simple Interest | Compound Interest |
|---|---|
| Starts with the original principal | Uses the growing account balance |
| Keeps the interest calculation tied to the principal | Allows earlier interest to contribute to future growth |
| Usually creates steady growth | Can create increasingly faster growth |
| Works with a straightforward calculation | Depends on the compounding schedule |
At first, the difference may look small. However, over a longer period, compound growth can create a much larger gap.
Why This Difference Matters
When you compare savings accounts, investments, or loans, do not focus only on the advertised interest rate. Instead, check how the provider calculates interest and how often the calculation occurs.
Also, consider the length of time involved. A small difference can become more noticeable when the balance continues to grow for many years.
Final Thoughts
Simple interest and compound interest follow two different paths. Simple interest keeps the calculation connected to the original principal. Compound interest, on the other hand, can build on earlier interest as the balance grows.
Once you understand how each method works, you can read financial terms more clearly and make more informed comparisons between different products.